 Posted by
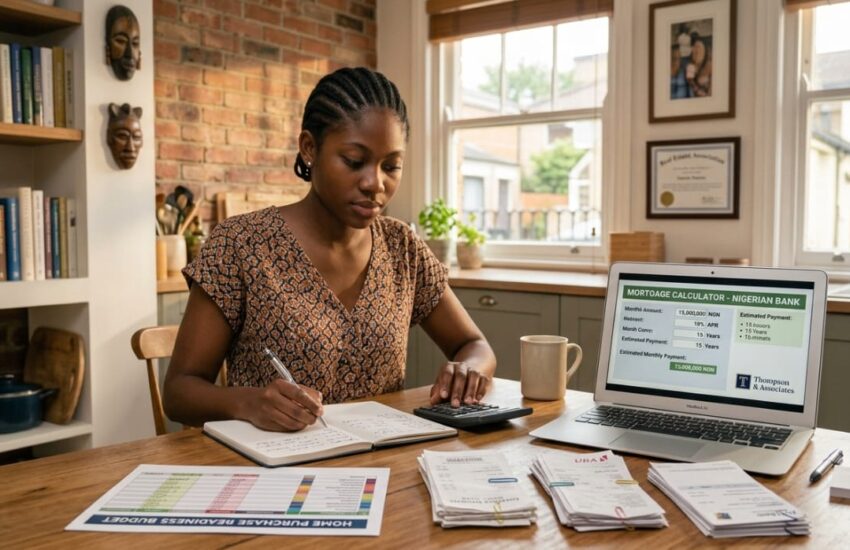
When I started house hunting, I did what most people do. I went online, found a mortgage calculator, and typed in my income. The number that popped up looked generous. I felt confident. I started touring homes in that price range. Then I met with a lender, and the reality hit me. The number I could qualify for was not the same as the number I could comfortably afford. I had been looking at homes that would have stretched me to the breaking point.
Determining your budget for buying a house is not about what a bank is willing to lend you. It is about what you can actually afford to pay each month without sacrificing your financial security, your sanity, or your quality of life. I learned that lesson the hard way, and it changed how I approached the entire process.
The first thing I learned is that your budget must start with your monthly expenses, not just your income. I tracked every dollar I spent for three months. Rent, utilities, groceries, transportation, subscriptions, dining out, medical expenses, and everything in between. Seeing it all on paper was humbling. I realized how much I was spending on things I did not even notice. That awareness was essential. You cannot know what you can afford if you do not know what you are already spending.
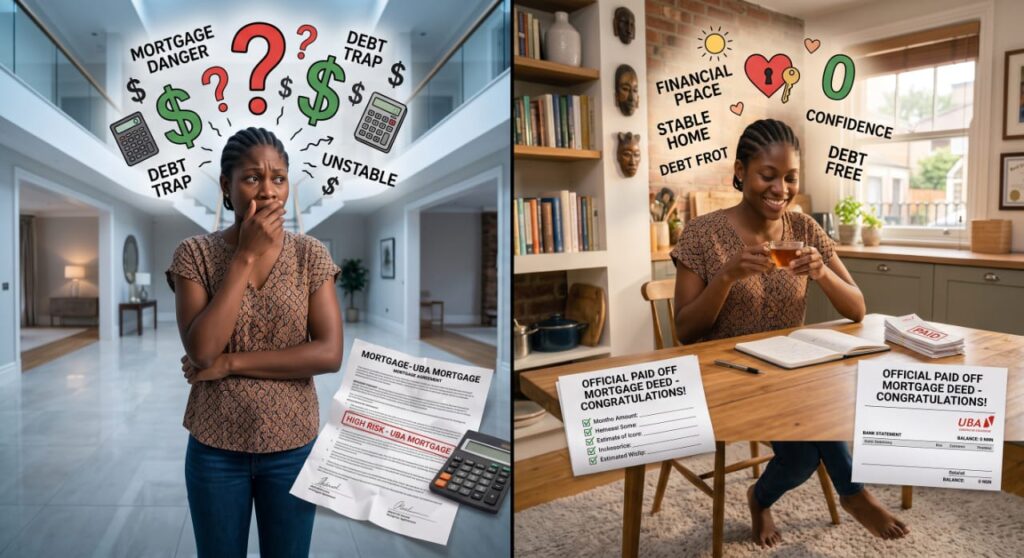
The second thing I learned is the difference between pre-approval and pre-qualification. Pre-qualification is a quick estimate based on self-reported information. Pre-approval is a formal review of your finances by a lender. It carries more weight with sellers, and it gives you a more accurate picture of what you can borrow. But even a pre-approval letter is not a budget. It is a maximum. It does not account for the life you want to live.
The third thing I learned is that your mortgage payment is not just the principal and interest. It includes property taxes, homeowners insurance, and possibly private mortgage insurance. It may also include HOA fees if you buy in a community with shared amenities. I added all of these costs to my budget before I looked at a single home. That number was the true monthly cost of ownership. It was higher than I expected.
The fourth thing I learned is the importance of a down payment. A larger down payment reduces your monthly payment and may eliminate the need for private mortgage insurance. It also gives you immediate equity in your home. I saved aggressively for my down payment, and it paid off. I was able to put down enough to avoid PMI and keep my monthly payment manageable. Even if you cannot put down twenty percent, every dollar helps.
The fifth thing I learned is that closing costs are significant. They typically range from two to five percent of the purchase price. That includes lender fees, appraisal costs, title search and insurance, and prepaid taxes and insurance. I created a separate savings account for closing costs. I did not want to deplete my emergency fund or rely on credit cards to cover them.
The sixth thing I learned is that an emergency fund is non-negotiable. When you own a home, things break. The furnace dies in January. The roof leaks after a storm. The water heater gives out. I kept three to six months of living expenses in a separate account. That fund saved me from financial panic when my first repair bill arrived. It also gave me confidence. I knew I could handle the unexpected.
The seventh thing I learned is to account for the ongoing costs of homeownership that renters never think about. Lawn care. Pest control. Painting. Replacing appliances. Cleaning gutters. These costs add up. I built them into my monthly budget so they did not become emergencies. I also learned to separate needs from wants. I needed a functioning roof. I wanted new light fixtures. Those were different budget lines.
The eighth thing I learned is that lenders do not know your life. They do not know that you plan to start a family, go back to school, or care for an aging parent. They do not know that you value travel or that you want to retire early. Your budget must reflect your life, not just your debt-to-income ratio. I chose a smaller home than I could technically afford because I wanted to keep my life. I wanted to sleep at night. I wanted to retire one day.
If you are preparing to buy a home, start with your actual spending. Talk to a lender to understand what you can borrow, but do not stop there. Add up the true monthly cost of ownership. Save for your down payment, your closing costs, and your emergency fund. Build in the ongoing costs of maintenance. And then decide what you are comfortable paying. That number is your budget. Everything else is just a calculation.
There is so much more to learn about preparing for homeownership. Our website is filled with articles on mortgages, down payments, and financial planning. Head over and explore, because a home should be a foundation, not a financial burden.
References
Consumer Financial Protection Bureau. (2026, February 17). *Figure out how much you want to spend*. [https://www.consumerfinance.gov/owning-a-home/prepare/figure-out-how-much-you-want-to-spend/](https://www.consumerfinance.gov/owning-a-home/prepare/figure-out-how-much-you-want-to-spend/)
Wallace, J. (2026, January 25). *How to calculate your budget*. *The Wall Street Journal*. [https://www.wsj.com/buyside/personal-finance/mortgage/how-much-house-can-i-afford](https://www.wsj.com/buyside/personal-finance/mortgage/how-much-house-can-i-afford)
NerdWallet. (2021, April 6). *How to budget for a new home so you don’t end up house poor*. [https://www.nerdwallet.com/mortgages/learn/how-to-keep-from-being-house-poor](https://www.nerdwallet.com/mortgages/learn/how-to-keep-from-being-house-poor)
Fidelity Investments. (2025, May 10). *How much house can I afford?* [https://www.fidelity.com/viewpoints/personal-finance/before-buying-house](https://www.fidelity.com/viewpoints/personal-finance/before-buying-house)
University of Missouri Extension. (2009, June 22). *Homebuyer’s resource guide: Home ownership made easier*. [https://extension.missouri.edu/publications/gh5002](https://extension.missouri.edu/publications/gh5002)
Rocket Money. (2022, September 11). *How much mortgage can I afford? A home-buying budget guide*. [https://www.rocketmoney.com/learn/homeownership/how-much-house-can-i-afford](https://www.rocketmoney.com/learn/homeownership/how-much-house-can-i-afford)