 Posted by
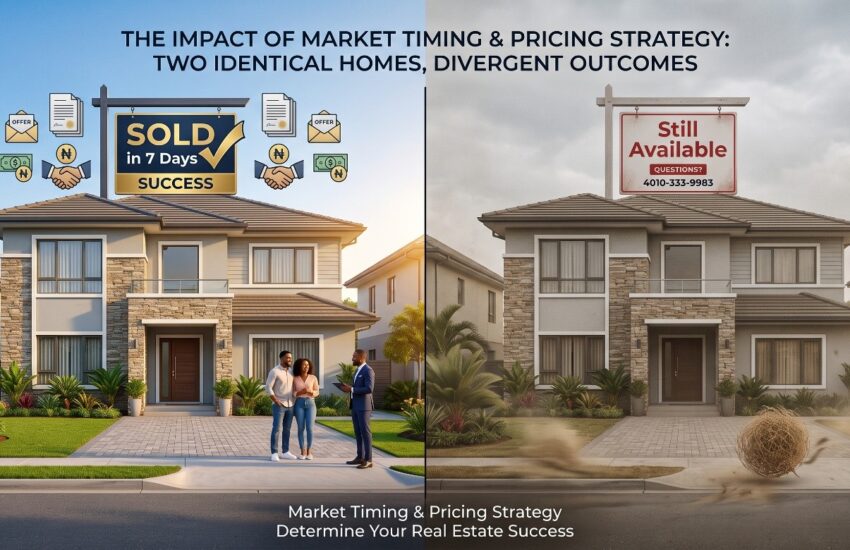
The spring I decided to sell my house, my neighbor listed hers two weeks before me. Her home was nearly identical to mine. Same square footage. Same layout. Same school district. She priced hers at what felt like an ambitious number and had three offers above asking within a week. I priced mine slightly higher and waited. And waited. Three weeks passed with only one showing. When I finally dropped my price, I had already lost the momentum she had captured. The difference was not the house. The difference was timing and understanding the market I was actually in, not the one I wished I was in.
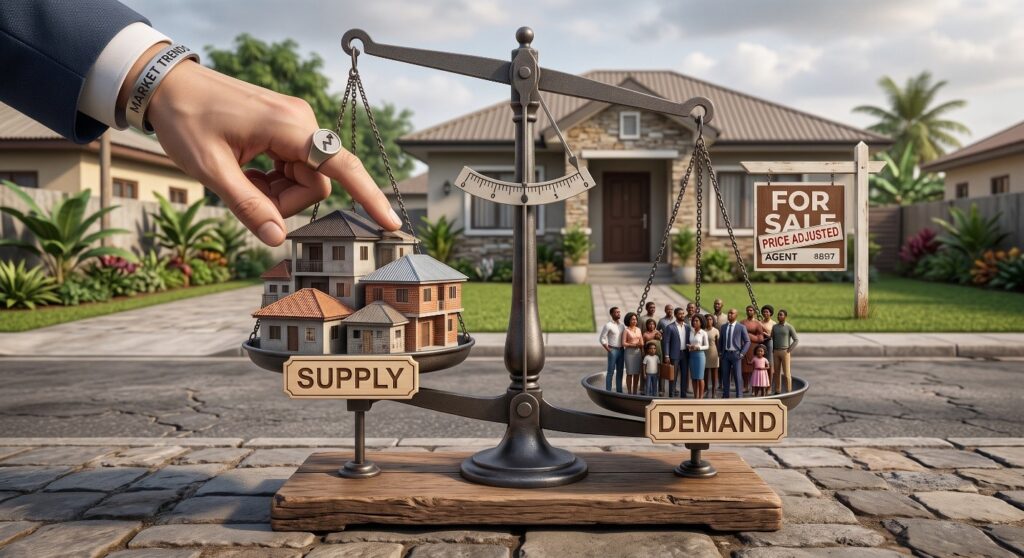
Selling a home is not just about preparing the property and finding a buyer. It is about understanding the forces that shape every transaction: supply and demand. When demand is high and supply is low, sellers hold the power. When supply is high and demand is low, buyers do. The same house can sell for wildly different prices and timelines depending on which side of that equation is currently in control. Ignoring these forces does not make them disappear. It just means they work against you instead of for you.
The first thing I had to accept was that the market does not care about my timeline, my financial goals, or my emotional attachment to the house. It only cares about what buyers are willing to pay and what other sellers are offering. My neighbor succeeded because she priced her home based on what the market was telling her, not based on what she wanted. She understood that in a seller’s market, homes priced correctly attract multiple offers, and multiple offers drive prices up. I understood that too late.
Inventory levels are the clearest signal of which market you are in. When there are fewer homes for sale than there are buyers looking, inventory is low, and sellers have leverage. Homes sell quickly. Buyers compete. Prices rise. When inventory is high, buyers have choices, and sellers must compete for attention. Overpricing in a high-inventory market is a death sentence. Your home sits while others sell, and the longer it sits, the more buyers assume something is wrong with it.
Days on market is another critical metric. In a balanced market, a well-priced home might sell in thirty to forty-five days. In a hot market, it might sell in a week. In a slow market, it might take months. These numbers are not just statistics. They are a countdown clock on your negotiating power. The longer your home sits, the more likely you are to receive lowball offers and requests for concessions. Momentum matters, and momentum is lost when a listing lingers.
Interest rates influence demand more than almost any other factor. When rates are low, buyers can afford more house for the same monthly payment, which increases demand and supports higher prices. When rates rise, affordability drops, buyer pools shrink, and sellers must adjust expectations. I learned to watch rate trends as closely as I watched comparable sales. A rate hike during my listing period meant fewer buyers walking through my door.
Seasonality also plays a role. Spring and summer are traditionally the busiest seasons for real estate, with more buyers actively searching and more sellers listing. Fall and winter are slower, with fewer buyers but also less competition. Selling in a slower season can work in your favor if you price correctly and market aggressively, because you are competing against fewer homes. But you must be realistic about the smaller buyer pool.
The most practical lesson I learned was to price ahead of the market, not behind it. Sellers who price based on what comparable homes sold for three months ago are often behind the curve. The market has already shifted. Pricing slightly below the expected sale price can generate multiple offers and drive the final number higher than if you had priced at the top of your range. It is counterintuitive, but it works. Buyers perceive value, competition builds, and the market sets the price.
Understanding market trends is not about predicting the future. It is about reading the present with clarity and honesty. It is about knowing when you have leverage and when you do not. It is about pricing strategically, marketing aggressively, and adjusting quickly when the data tells you something different than your hopes.
My second home sold in nine days. I had learned my lesson. I priced it based on what the market was telling me, not what I wanted to hear. The offers came in fast, and I closed above asking. The market had not changed. I had.
References
Federal Reserve Board. (2025, July 16). *A view of the housing market and U.S. economic outlook*. [https://www.federalreserve.gov/newsevents/speech/kugler20250717a.htm](https://www.federalreserve.gov/newsevents/speech/kugler20250717a.htm)
Federal Reserve Board. (2026, September 22). *Speech by Governor Barr on housing*. [https://www.federalreserve.gov/newsevents/speech/barr20260923a.htm](https://www.federalreserve.gov/newsevents/speech/barr20260923a.htm
National Association of REALTORS®. (2024, December 12). *Research and statistics*. [https://www.nar.realtor/research-and-statistics](https://www.nar.realtor/research-and-statistics)
National Association of REALTORS®. (2025, August 13). *Listing price reduction? How to navigate it with buyers and sellers*. [https://www.nar.realtor/news/real-estate-news/sales-marketing/listing-price-reduction-how-to-navigate-it-with-buyers-sellers](https://www.nar.realtor/news/real-estate-news/sales-marketing/listing-price-reduction-how-to-navigate-it-with-buyers-sellers)
Congressional Research Service. (2026). *Housing supply: Current trends and policy considerations*. [https://www.congress.gov/crs_external_products/R/PDF/R48892/R48892.2.pdf](https://www.congress.gov/crs_external_products/R/PDF/R48892/R48892.2.pdf)
U.S. Bank. (2026, September 21). *The impact of today’s interest rates on the housing market*. [https://www.usbank.com/investing/financial-perspectives/investing-insights/interest-rates-impact-on-housing-market.html](https://www.usbank.com/investing/financial-perspectives/investing-insights/interest-rates-impact-on-housing-market.html)
Federal Reserve Bank of Cleveland. (2024, February 26). *Comparing two house-price booms*. [https://www.clevelandfed.org/publications/economic-commentary/2024/ec-202404-comparing-two-house-price-booms](https://www.clevelandfed.org/publications/economic-commentary/2024/ec-202404-comparing-two-house-price-booms)